Credit Repair · September 18, 2026
Get Better Credit: Dealing with Collections
Part 3 of Get Better Credit Series.
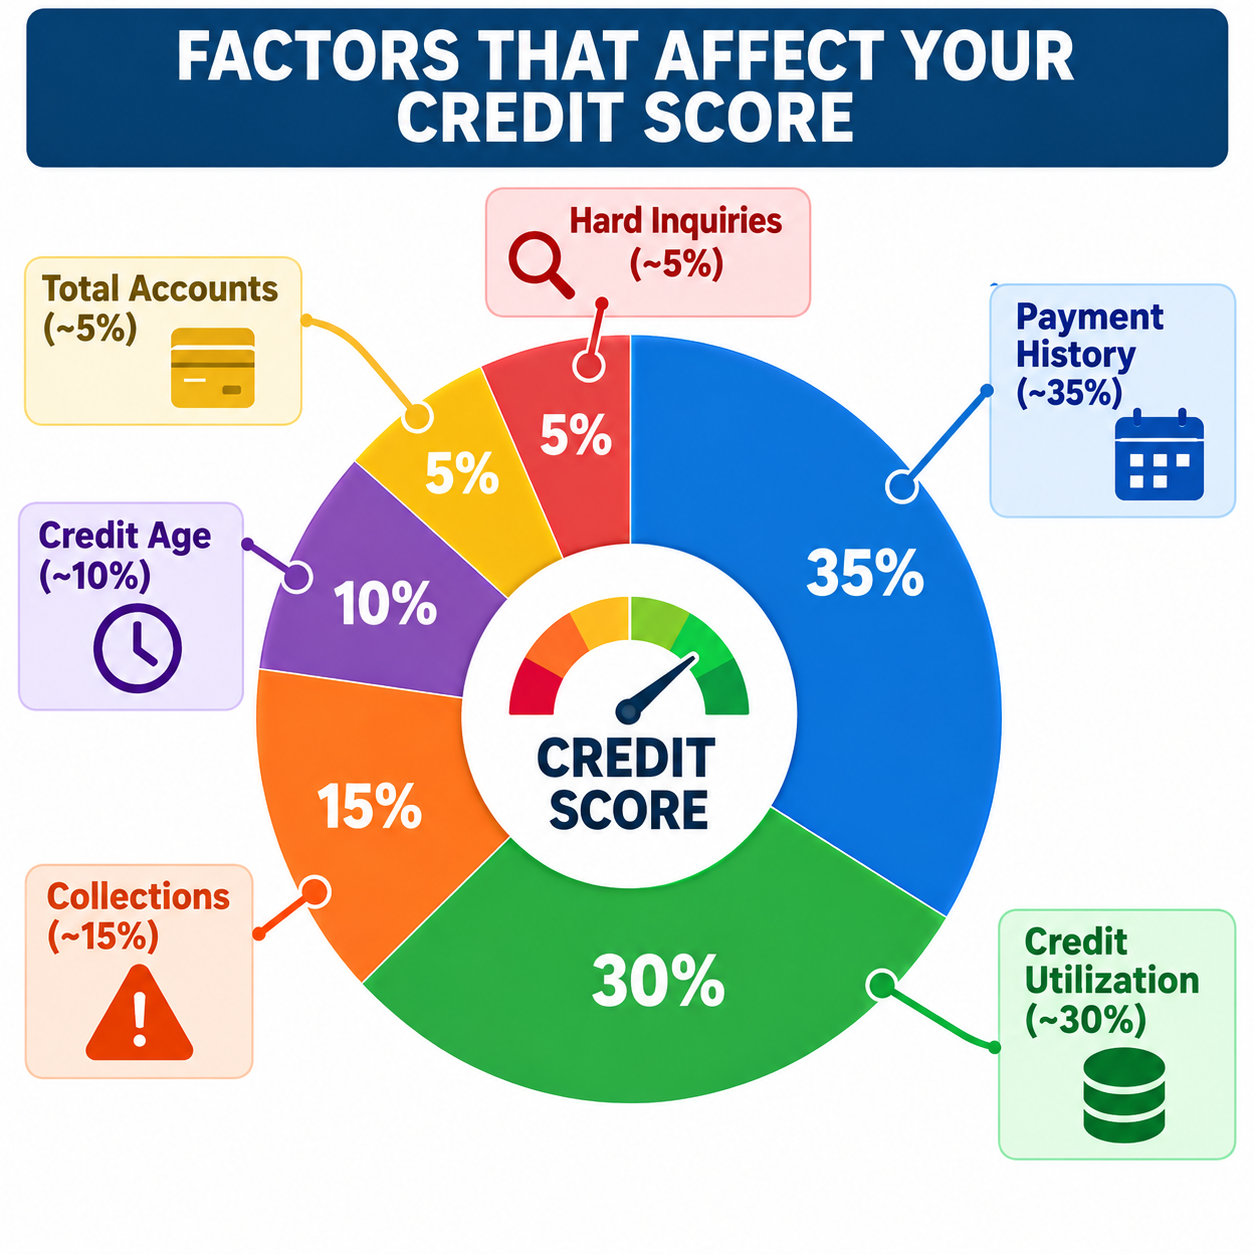
Part 3: Dealing with Collections (And How to Negotiate Them Off Your Report!)
Welcome back to our credit series at idoletsgo.com! Today, we are tackling one of the most intimidating topics in personal finance: Collections.
If an unpaid bill gets sent to a collection agency, it can feel overwhelming. But understanding how the collections industry actually works gives you incredible leverage to negotiate settlements, erase marks from your credit report, and save hundreds—or even thousands—of dollars.
How Collections Work: Debt Bought for Pennies
When you owe money on an account (like a credit card, medical bill, or utility) and it goes unpaid for several months, the original creditor eventually writes it off as a loss. They then sell your debt to a third-party collection agency.
Here’s the secret collectors don't want you to know: collection agencies buy debt for pennies on the dollar.
A collection agency might buy a $1,000 delinquent debt for as little as $40 to $100 (4% to 10% of the original amount). Because they bought your debt so cheaply, they do not need you to pay the full balance to make a massive profit. Everything you pay over what they bought it for is pure income for them, which makes them very willing to negotiate.
Rule #1: Medical Debt Is Different (And Erased When Paid!)
If your collection account is for medical debt, you are in luck thanks to major rule changes implemented by the nationwide credit bureaus (Equifax, Experian, and TransUnion):
Automatic Eradication Upon Payment: Unlike standard credit card debt, as soon as a paid or settled medical collection account is marked as $0 balance, it must be completely erased from your credit report automatically.
Small Balances Excluded: Unpaid medical collections under $500 no longer appear on credit reports at all.
1-Year Waiting Period: Medical debt cannot be reported on your credit file until it has been delinquent for at least 1 full year, giving you plenty of time to work with insurance or healthcare providers before your score takes a hit.
If you have a medical collection over $500, negotiating a low settlement amount will completely remove the mark from your credit profile once it's marked as paid.
How to Get Regular Collections Erased: The "Pay-for-Delete" Strategy
For non-medical collections (like credit cards, personal loans, or cell phone bills), simply paying off the collection isn't always enough. A paid collection can still sit on your report marked as "Paid Collection," which continues to drag down your score.
To get regular collections completely wiped off your credit report, you need to negotiate a "Pay-for-Delete" agreement.
How Pay-for-Delete Works:
Never Pay Full Price: Start by offering to settle the debt for 20% to 30% of the total amount owed.
Require Deletion as a Condition: State clearly that you will only pay the agreed settlement amount if the collection agency agrees in writing to completely delete the collection account from all three credit bureaus.
GET IT IN WRITING FIRST: Never give a collection agency your bank account info or send a single dollar over the phone until you have a signed written agreement (via email or mail) stating that the account will be deleted upon receipt of payment.
The 7-Year Expiration Date: The Clock Is Always Ticking
If a collector refuses to negotiate a Pay-for-Delete, or if you simply cannot afford to pay, remember that collections do not stay on your credit report forever.
The 7-Year Rule: Under the Fair Credit Reporting Act (FCRA), negative collection accounts must legally fall off your credit report 7 years from the date of the original delinquency (when you first missed a payment with the original creditor).
Beware of "Re-Aging": Making a partial payment on an old debt can reset the state statute of limitations for being sued, but it does not reset the 7-year federal credit reporting clock. The 7-year clock strictly runs from your first missed payment date.
If a collection account is already 5 or 6 years old, it may be better to let the 7-year clock run out naturally rather than paying money for an old debt that is about to drop off your score anyway.
Summary Checklist for Handling Collections:
Medical Debt? Negotiate a low payout; once paid, it automatically disappears from your score.
Regular Debt? Negotiate for 20%–50% of the total balance and insist on a written Pay-for-Delete letter before paying.
Old Debt? Check the date of original delinquency. If it's close to 7 years old, let time do the work.
Stay tuned to idoletsgo.com for more practical guides on navigating credit, travel rewards, and financial freedom!
Ready to find your card?
Answer a few questions and we'll match you with the cards that fit your plans.
GET YOUR RECOMMENDATION